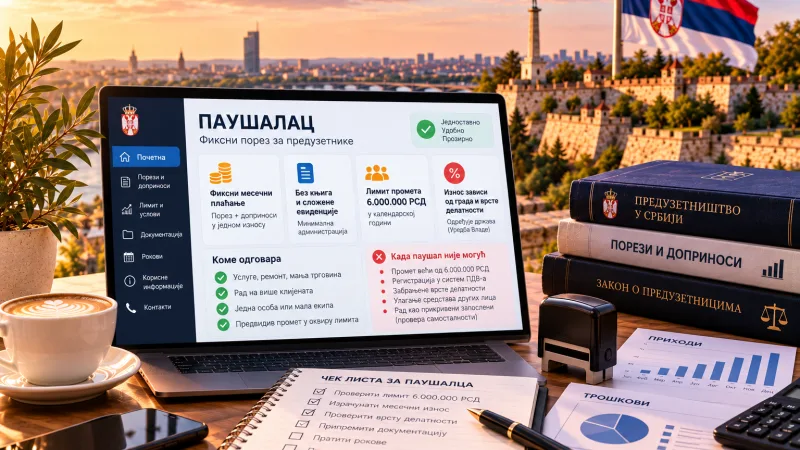
A flat-rate entrepreneur — paushalac — pays tax not on actual income but as a fixed sum. The state sets that sum: it depends on the city where the activity is registered and on the type of activity, and it is calculated under a government decree. Payment is monthly, and the amount is stated in the tax administration's decision.
What the fixed payment covers
Unlike an employee, a flat-rate entrepreneur pays both tax and contributions out of his own pocket — but in a single sum rather than by calculating it from every payment. He keeps no account books, reporting is minimal, and an accountant is usually needed only for annual formalities. It is precisely this simplicity that makes the regime popular with people who work for themselves, alone or with a small team.
The 6,000,000 dinar limit
The main constraint is turnover. As long as total income in a calendar year does not exceed 6,000,000 dinars, the right to flat-rate taxation remains. Once turnover is higher, the regime ends and the entrepreneur moves to taxation on income actually earned. This is a fundamental difference from the VAT threshold: 6,000,000 is the flat-rate limit, while 8,000,000 over 12 months is the threshold for mandatory VAT registration. The two figures are often confused.
When the right to the flat rate is lost
The law lists several grounds for the regime to end: exceeding the turnover, being registered in the VAT system, changing to an activity that excludes flat-rate taxation, and investment by other persons into the business. The list of activities the flat rate does not cover is set by law: it includes, for example, advertising and market research, while in trade and catering the regime is available only when operating from a mobile unit.
The independence test
A separate subject is the so-called independence test. If an entrepreneur works in practice for a single client for years and everything about the arrangement resembles employment, the income may be recalculated as another type of income, with different tax and contributions. The reference point is a set of criteria assessing how independent the work is: who sets the schedule, who pays the expenses, whose tools and equipment the performer uses. It is important to remember that income recalculated this way does not count towards the 6,000,000 limit.
Who it suits
The flat rate suits those whose turnover is predictable and stays within the limit: services, repairs, small trade, work for several clients. If turnover grows and approaches the ceiling, it is worth working out the options in advance: remain a sole trader but move to books, or found a company. Both should be planned before the limit is breached, so the change passes calmly rather than in a rush.