Hiring an employee in Serbia costs more than the salary they take home. The employer pays contributions for them, and tax is withheld from the payment. Here is what the total is made of and what has to be done every month.
The salary tax
The tax rate on income from work is 10%. There is also a non-taxable portion: it is deducted from the base every month and in 2026 amounts to 34,221 dinars. So tax is levied not on the whole salary but on the part above that sum.
Contributions: 35.05% on the total
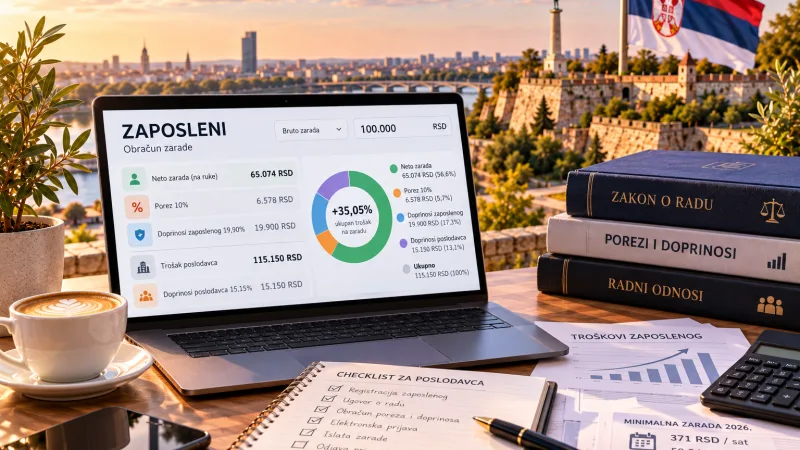
Mandatory social insurance contributions are paid by both sides on the same base. The employee gives 19.90%: 14% for pension and disability insurance, 5.15% for health and 0.75% for unemployment insurance. The employer adds 15.15%: 10% for pension and 5.15% for health. In total, 35.05% is added to the payroll — the key figure for budgeting.
The 2026 minimum wage
The minimum price of labour is 371 dinars net per working hour, as set by a government decision. There is no fixed monthly amount: everything depends on the number of working hours in the month. For 160 hours the minimum take-home wage is 59,360 dinars; for 168 hours it is 62,328 dinars. In a month with more hours the sum is proportionally higher.
The employer's obligations
The tax and contributions are calculated and paid by the employer — at every salary payment. Registration also takes steps: the employee must be registered and the calculation filed electronically. A month after work begins there is no 'we will settle it later': the obligation arises with the first payment.
If the employee is a foreigner
For a foreign employee a contract alone is not enough: a work and residence permit is required, and these are now issued as a single permit. The procedure takes time, so the application is filed in advance, before work starts. The mere existence of a company, or a foreign owner, does not entitle the employee to work.
What to keep in mind when hiring
First — budget not by take-home pay but by the full amount including contributions. Second — remember that the non-taxable portion is deducted from the base each month, not once a year. Third — do not confuse the minimum hourly rate with the full minimum wage: they are linked through the number of hours. And fourth — when an employee leaves, that too must be handled on paper and on time.